Prof. Dr. To Trung Thanh: How Can Declining CAR and Asset Quality in the Banking System Be Addressed?
12/05/2025 2025-05-12 17:38Prof. Dr. To Trung Thanh: How Can Declining CAR and Asset Quality in the Banking System Be Addressed?
Prof. Dr. To Trung Thanh: How Can Declining CAR and Asset Quality in the Banking System Be Addressed?
In an interview with the Journal of Economics and Finance, Prof. Dr. To Trung Thanh, Head of the Department of Research Management at National Economics University (NEU), proposed a range of solutions for the banking sector to develop sustainably amid economic volatility.
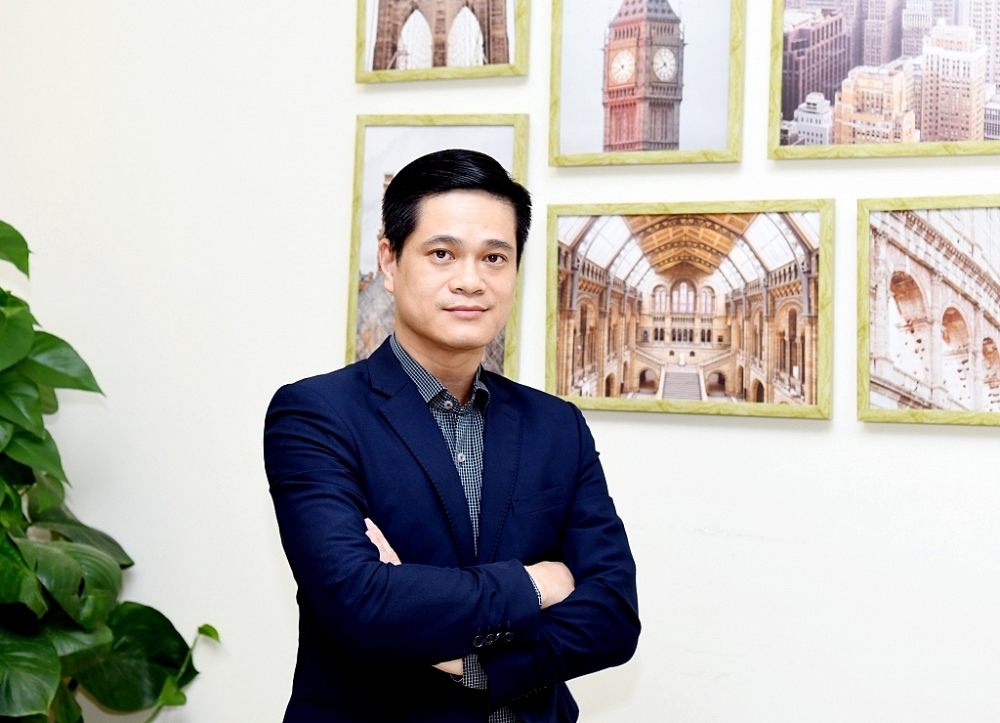
Prof. Dr. To Trung Thanh, Head of the Department of Research Management, NEU
Reporter: How do you assess the current quality of the banking system?
Prof. Dr. To Trung Thanh: According to research in NEU’s Vietnam Annual Economic Review 2024, Vietnam’s banking system currently faces numerous challenges, particularly a marked divergence in capital adequacy ratios (CAR) between two groups of banks.
The threat of liquidity risk emerged in the banking system in 2024, as the sector-wide loan-to-deposit ratio (LDR) continued to rise because lending growth outpaced growth in customer deposits.
Also affecting funding costs, the current account and savings account (CASA) ratio at many banks has tended to decline, forcing banks to rely on longer-term funding sources with higher interest rates, increasing funding costs and narrowing net interest margins (NIM).
While banks calculating CAR under the State Bank of Vietnam’s (SBV) Circular No. 41/2016/TT-NHNN are making considerable efforts to improve their capital adequacy ratios beyond the required 8%, the ratio among banks calculating CAR under Circular No. 22/2019/TT-NHNN has been declining and is currently below the required threshold of 9%.
The main reason lies in the pace of charter capital growth. Joint-stock commercial banks generally take the initiative to increase capital faster than banks with state capital, thereby maintaining higher CAR levels.
However, with the stock market subdued, raising capital through share issuance has become difficult. Many banks are turning to capital-raising methods such as paying dividends in shares, which is gradually becoming a trend among banks.
Meanwhile, asset quality in the banking system is deteriorating. The system’s nonperforming loan ratio has continued to rise since 2023, albeit at a slower pace, while provisions for loans classified as losses have declined. Moreover, banks face numerous obstacles in resolving nonperforming loans. The real estate market remains subdued, and many banks have stepped up asset liquidation to recover debts. However, weak liquidity means that many high-value properties remain unsold despite steep price reductions.
Beyond market factors, institutional mechanisms have also slowed the resolution of nonperforming loans. The failure to incorporate certain important provisions of the National Assembly’s Resolution No. 42/2017/QH14 on the pilot resolution of nonperforming loans into the 2024 Law on Credit Institutions has limited the rights of entities handling debt resolution.
Reporter: What policies do you think banks need to ensure sustainable development, particularly as monetary policy is being eased to support economic growth?
Prof. Dr. To Trung Thanh: For the banking system to develop sustainably, policymakers need to focus on two groups of solutions: strengthening financial soundness and conducting monetary policy flexibly.
Accordingly, banks, particularly commercial banks with state capital, need to step up improvements in their capital adequacy ratios to reach at least 11–12% under Basel II standards, while moving toward readiness for new Basel III requirements as outlined in the draft circular regulating CAR for commercial banks and foreign bank branches.
At the same time, charter capital increases must be completed to reach a minimum of VND 15,000 billion for commercial banks with substantial financial resources and VND 5,000 billion for the remaining group.
Credit institutions need to strengthen efforts to prevent new nonperforming loans by maintaining credit standards, reinforcing risk management, and improving early warning systems for nonperforming loans.
Banks need support to resolve nonperforming loans thoroughly and effectively, including optimizing the use of provisions, applying legal measures to recover debts effectively, and promoting the trading and resolution of nonperforming loans through the Vietnam Asset Management Company (VAMC) and other debt trading companies.
Regulators, particularly the SBV, need to develop the banking market by enhancing competitiveness, increasing transparency, and ensuring compliance with international standards and practices in the governance and operations of credit institutions, such as Basel III.
Alongside this, they must ensure the safety of banking operations and continue corrective measures and restructuring at weak banks to restore their financial health, strengthen their financial capacity in terms of scale, quality, and efficiency, and ensure the safety of the system. They must also comprehensively review other laws relating to the resolution of nonperforming loans and the disposal of collateral securing those loans.
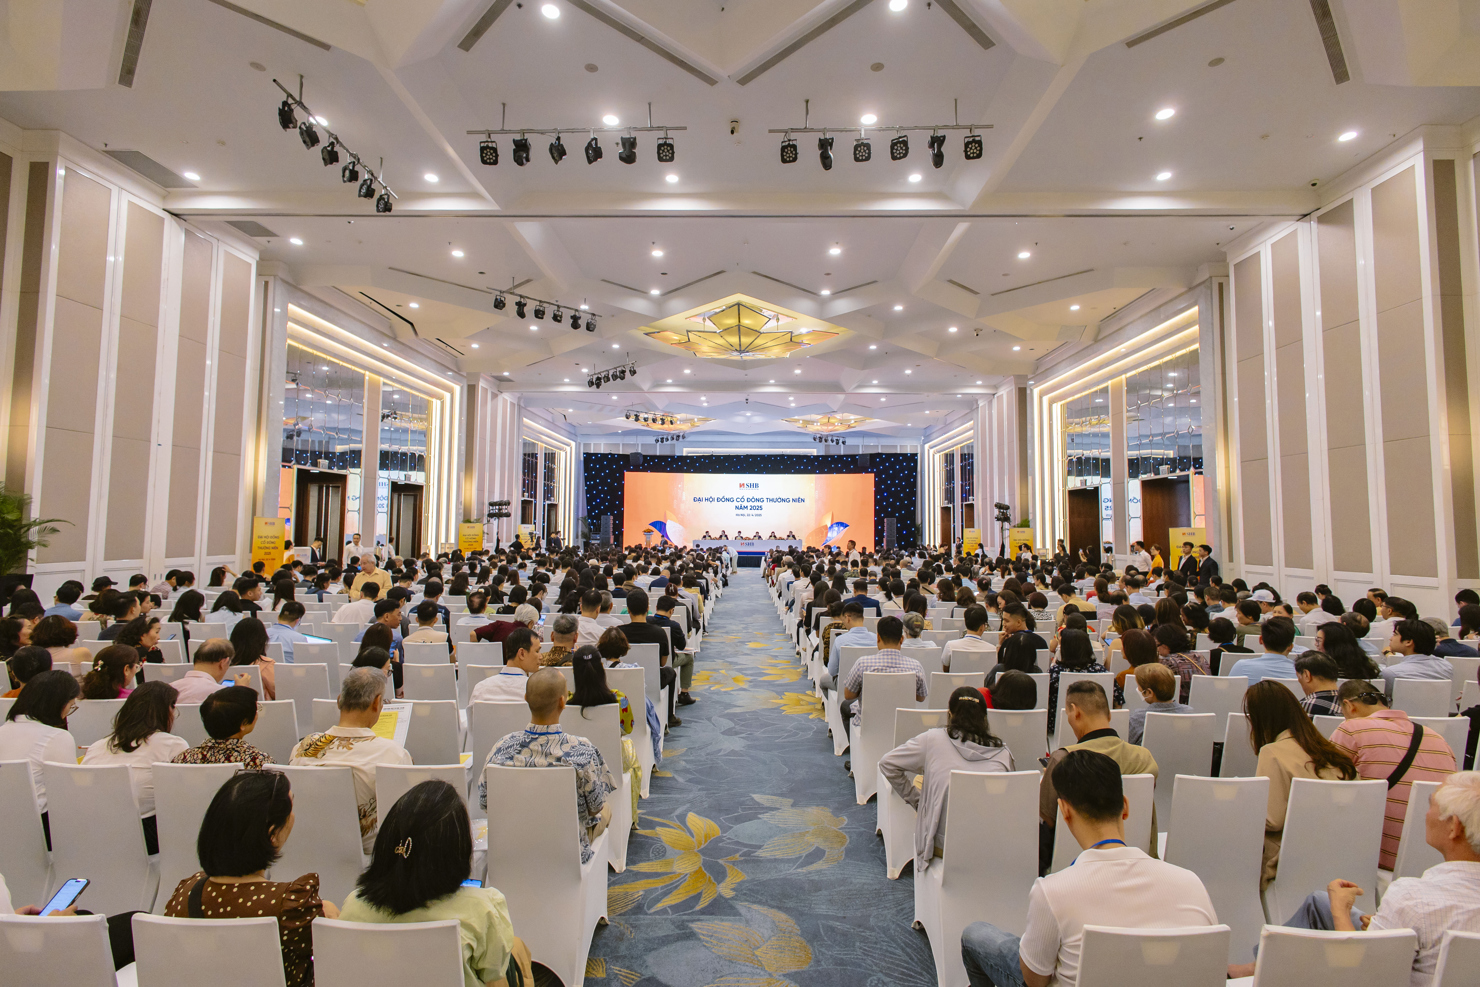
Banks’ 2025 annual general meetings of shareholders highlighted numerous opportunities and challenges in the current context. Photo: SHB’s general meeting of shareholders.
Regarding monetary policy, the SBV needs to keep credit growth at 16% in 2025, prioritize capital flows into production, high-tech agriculture, and green credit, and strictly control credit to potentially risky sectors. In particular, legal barriers need to be removed to encourage banks to participate in social housing lending.
Reporter: Regarding monetary policy, how should it be conducted to both control inflation and help banks reduce funding costs?
The SBV should further reduce reserve requirement ratios for credit institutions focusing on vulnerable customers, such as small and medium-sized enterprises and those in agriculture and rural areas, or reduce credit information inquiry fees at the Vietnam National Credit Information Center (CIC) and deposit insurance premiums. This would help credit institutions cut costs, thereby enabling further reductions in lending rates.
Prof. Dr. To Trung Thanh: Conducting monetary policy is a balancing act, guided by proactive and flexible action and close coordination with fiscal policy to control inflation, stabilize the macroeconomy, and support growth.
The SBV needs to continue implementing specific measures to reduce lending rates across the economy through monetary policy tools and regulatory measures within its mandate.
The SBV can adjust policy rates appropriately and require credit institutions to cut costs to further reduce lending rates, making it easier for businesses and individuals to access capital.
The SBV needs to manage the exchange rate flexibly to adapt to global shocks. In 2025, the greatest exchange rate risks continue to stem primarily from international issues, such as persistently high U.S. dollar interest rates, the continued strengthening of the U.S. dollar, geopolitical risks, U.S. tariff policy, and unpredictable trade wars.
The SBV needs to continue managing the exchange rate flexibly within an appropriate trading band and stand ready to use intervention tools to maintain stability during periods of intense pressure.
In the current context, the SBV’s administrative interventions need to be gradually removed, and the permissible exchange rate trading band should be widened further, moving toward a managed float when macroeconomic conditions permit.
Reporter: Thank you for sharing your insights!
Source: Journal of Economics and Finance
This is an automated translation. If you notice any errors, please contact the Department of Communications, National Economics University at phongtruyenthong@neu.edu.vn.